Oil has replaced AI as the market’s biggest worry, and Gold slipped below 4,000 even as Treasury yields fell. With the Fed, ECB, BoC, RBNZ and BoJ all deciding in one week, plus the UK Autumn Budget and US GDP, here is what to watch from October 26 to 30.
This Week at a Glance
Oil has replaced AI as the market's main worry. WTI pushed above 104 after Houthi attacks on Saudi Arabia, IRGC strikes on Hormuz shipping and reports of possible US-Israel strikes on Iran after the November 3 midterms.
Gold fell about 4% and broke below 4,000 for the first time in three months, even though Treasury yields dropped. The usual link between yields and Gold broke down.
The Fed, ECB, BoC, RBNZ and BoJ all decide within five trading days, alongside the UK Autumn Budget, US Q3 GDP and core PCE.
Last Week's Scoreboard
Instrument | Price | Weekly Change |
|---|
DXY | 101.51 | ▲ 0.05% |
EUR/USD | 1.1202 | ▼ 0.32% |
GBP/USD | 1.3373 | ▲ 0.35% |
Gold | 3,997 | ▼ ~4% |
WTI | 104.98 | ▲ 3.99% |
US500 | 7,632 | ▼ ~0.5% |
BTC/USD | 80,239 | ► ~flat |
Key Events This Week (GMT)
Day | Time | Event | Forecast / Prior | Impact |
|---|
Mon 26 Oct | – | Germany IFO Business Climate | – | ★★ |
Tue 27 Oct | 12:30 | US Durable Goods Orders | – | ★★ |
Tue 27 Oct | 14:00 | US CB Consumer Confidence | Prior: five-month low | ★★ |
Wed 28 Oct | 00:30 | Australia Q3 CPI | – | ★★ |
Wed 28 Oct | 01:00 | RBNZ Rate Decision | 25 bp hike exp. | ★★ |
Wed 28 Oct | – | UK Autumn Budget (no fixed time) | – | ★★★ |
Wed 28 Oct | 13:45 | BoC Rate Decision | 25 bp hike exp. | ★★★ |
Wed 28 Oct | 18:00 | Fed Rate Decision (Chair Kevin Warsh) | Hold exp. | ★★★ |
Wed 28 Oct | 18:30 | Fed Chair Warsh Press Conference | – | ★★★ |
Thu 29 Oct | 12:30 | US Q3 GDP (Advance), Core PCE (Sep), Initial Jobless Claims | GDP 3.0% exp. | ★★★ |
Thu 29 Oct | 13:15 | ECB Rate Decision | Hold exp. | ★★★ |
Thu 29 Oct | 13:45 | ECB President Lagarde Press Conference | – | ★★★ |
Fri 30 Oct | – | BoJ Rate Decision | Hold exp. | ★★★ |
Fri 30 Oct | 10:00 | Eurozone Q3 GDP Flash Estimate | – | ★★ |
Fri 30 Oct | 12:30 | US Employment Cost Index | – | ★★ |
Fri 30 Oct | 13:00 | Germany Preliminary CPI | – | ★★ |
Time zones: London is GMT (UK clocks went back on October 25), New York is GMT−4 (US daylight saving time runs until early November), Singapore/Hong Kong are GMT+8. For example, the Fed decision at 18:00 GMT is 18:00 in London, 14:00 in New York and 02:00 on Thursday in Singapore. The ECB decision at 13:15 GMT is 13:15 in London, 09:15 in New York and 21:15 in Singapore.
Market Sentiment Overview
This is the most concentrated central bank week of the series, and markets arrive with oil as the dominant worry. Houthi attacks on Saudi Arabia, IRGC strikes on shipping in the Strait of Hormuz, a tanker explosion after hitting a mine and reports of post-midterm US-Israel strike planning pushed WTI above 104 and Brent to its highest level since April. Rising energy prices are feeding inflation fears just as central banks meet. Markets expect the Fed and ECB to hold, but December hikes are priced near 75 to 80% for the Fed.
Gold's behavior was the week's most significant development: it fell about 4% and touched 3,975 despite the 10-year Treasury yield dipping below 5%. Thursday was its worst single day, down nearly 3%. US data stayed resilient, with jobless claims at a three-month low and October PMIs showing solid expansion, but consumer sentiment dropped to a five-month low as households cited high prices. The S&P 500 ended about 0.5% lower on AI spending fears (Thursday) and oil-driven pressure on consumer stocks (Friday). The November 3 midterms, just days after the FOMC, add a political layer to every oil headline.
Currencies
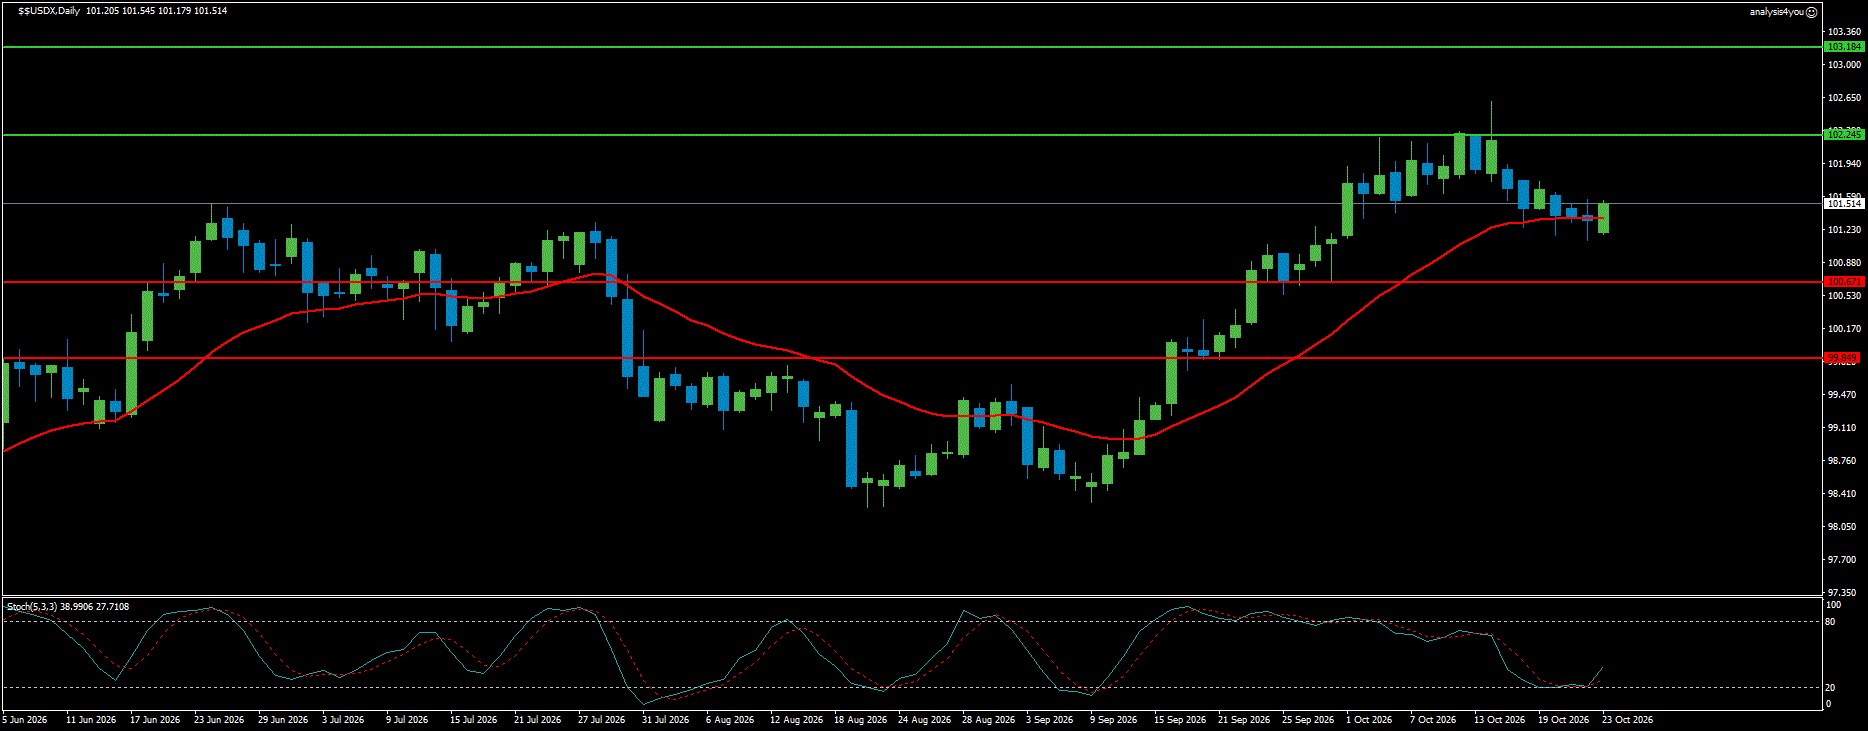
USD Index (DXY): Testing the 20-Day MA Into the Fed (101.51)
Trend: Bullish | Sentiment: Mixed
The Dollar Index ended roughly flat, up 0.05%. It briefly slipped to three-week lows near 101.50 as Treasury yields fell and AI-related stocks sold off, then recovered on solid US data. Price sits on the 20-day MA with the Stochastic turning up from oversold levels. Markets see less than a 10% chance of a Fed hike on Wednesday but about 75% odds for December. TD Securities argues that pausing now sets a high bar for avoiding a December hike, so Warsh's tone and the vote split matter more than the decision itself. A unanimous hold with hawkish guidance would favor the Dollar, while an emphasis on patience could soften it. Thursday brings US Q3 GDP and core PCE at the same time as the ECB decision.
Resistance: 102.25; 103.18 | Support: 100.67; 99.85
Bias: Holding the 20-day MA keeps the uptrend intact, and dissents in favor of a hike would point toward 102.25 and 103.18. A close below 100.67 would signal a deeper correction toward 99.85.
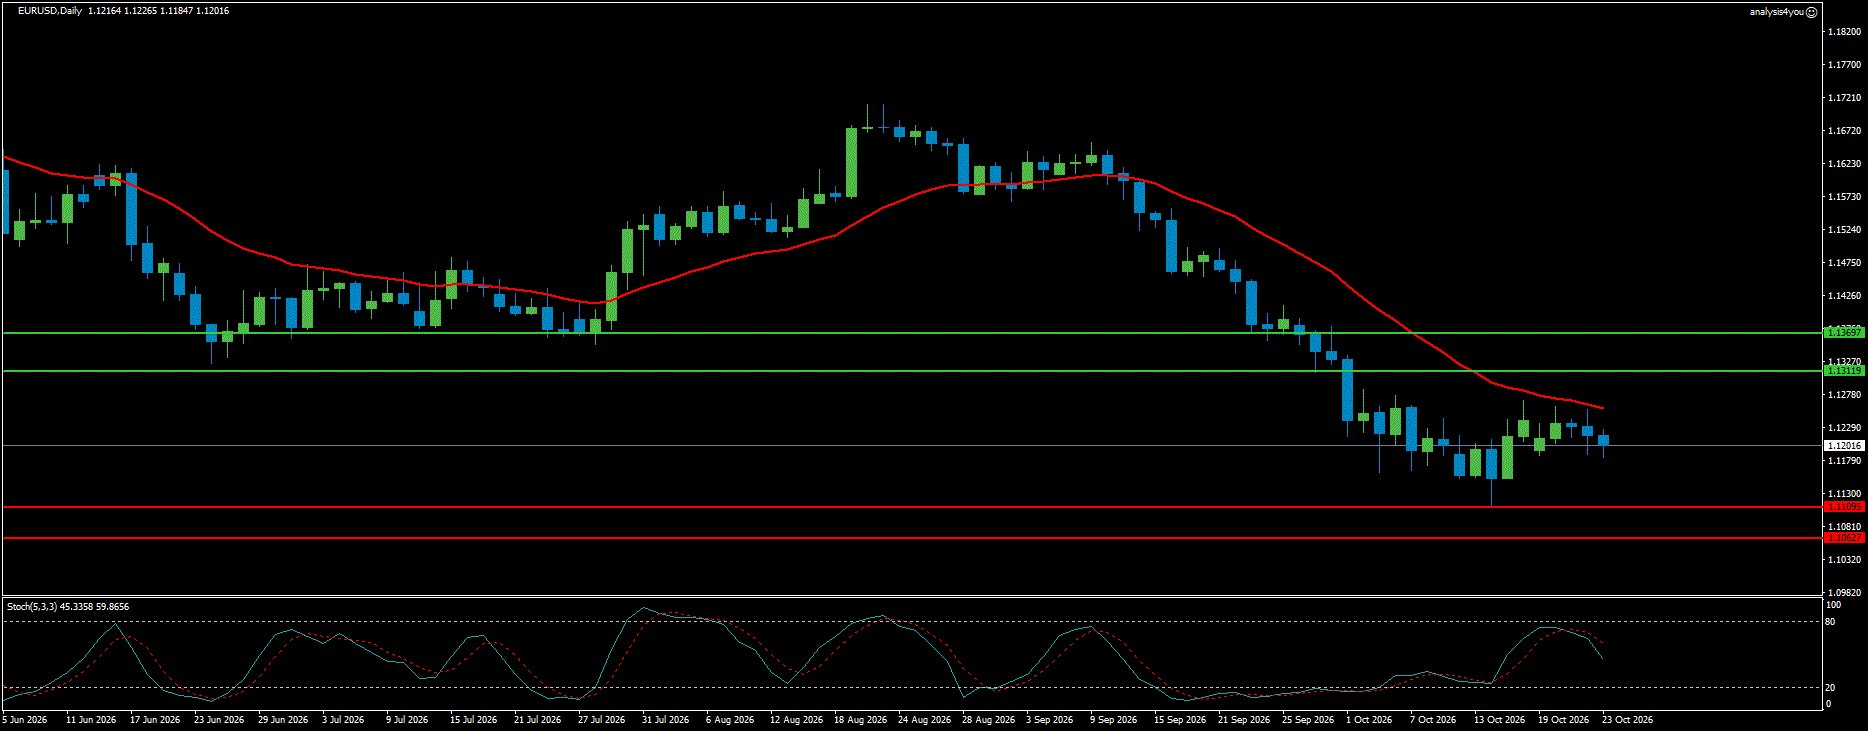
EUR/USD: 200-Week SMA Is the Last Structural Defense (1.1202)
Trend: Bearish | Sentiment: Negative
EUR/USD gave back the prior week's bounce and ended slightly lower, held back by French fiscal concerns. France's 10-year yield climbed above 5%, matching the US 10-year for the first time in decades. The pair holds just above the 200-week SMA near 1.1105, the last meaningful technical floor before the 1.1000 psychological level. Price remains below the falling 20-day MA with the Stochastic turning lower. Commerzbank expects both the Fed and ECB to pause now and hike in December, but says the ECB call depends on French bond stress not escalating. If Lagarde hints that French pressure is delaying a December hike, the Euro loses a key support pillar. If the December guidance holds, a temporary relief bounce is possible.
Resistance: 1.1312; 1.1370 | Support: 1.1109; 1.1063
Bias: A weekly close below the 200-week SMA near 1.1105 to 1.1109 would open 1.1063 and the 1.1000 handle. Rebounds toward 1.1312 face resistance while price stays below the 20-day MA.
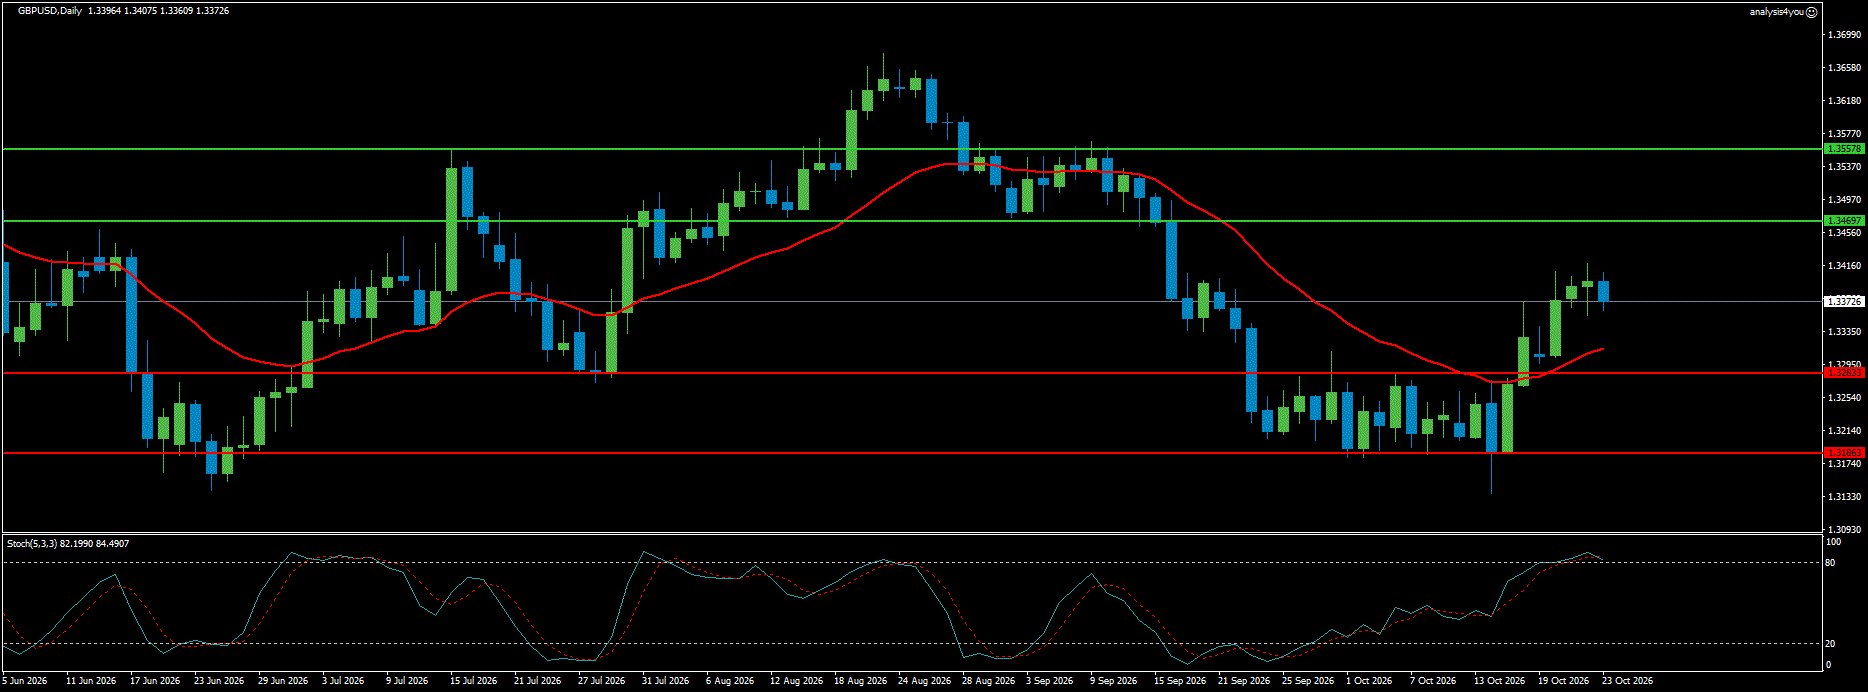
GBP/USD: Short-Covering Rally Meets the Autumn Budget (1.3373)
Trend: Bullish | Sentiment: Positive
Sterling rose for a second consecutive week, briefly climbing above 1.3400 after higher UK inflation and a hawkish BoE. CFTC data show speculators cutting GBP shorts to a five-week low, so short-covering rather than fresh buying is the main driver, which needs fundamental confirmation to extend. UK composite PMI rose to 53.1, but retail sales growth slowed to 0.8%, below expectations. Price holds above the rising 20-day MA, though the Stochastic is overbought, a warning of possible consolidation. Wednesday's Autumn Budget is the key event. PM Burnham framed it as giving businesses breathing space to grow. Credible deficit reduction alongside growth investment would support Sterling, while a surprise in gilt issuance could trigger a bond market reaction.
Resistance: 1.3470; 1.3558 | Support: 1.3283; 1.3186
Bias: A break above 1.3470 opens 1.3558. A pullback toward 1.3283 would still keep the recovery structure intact.
Stocks & Indices
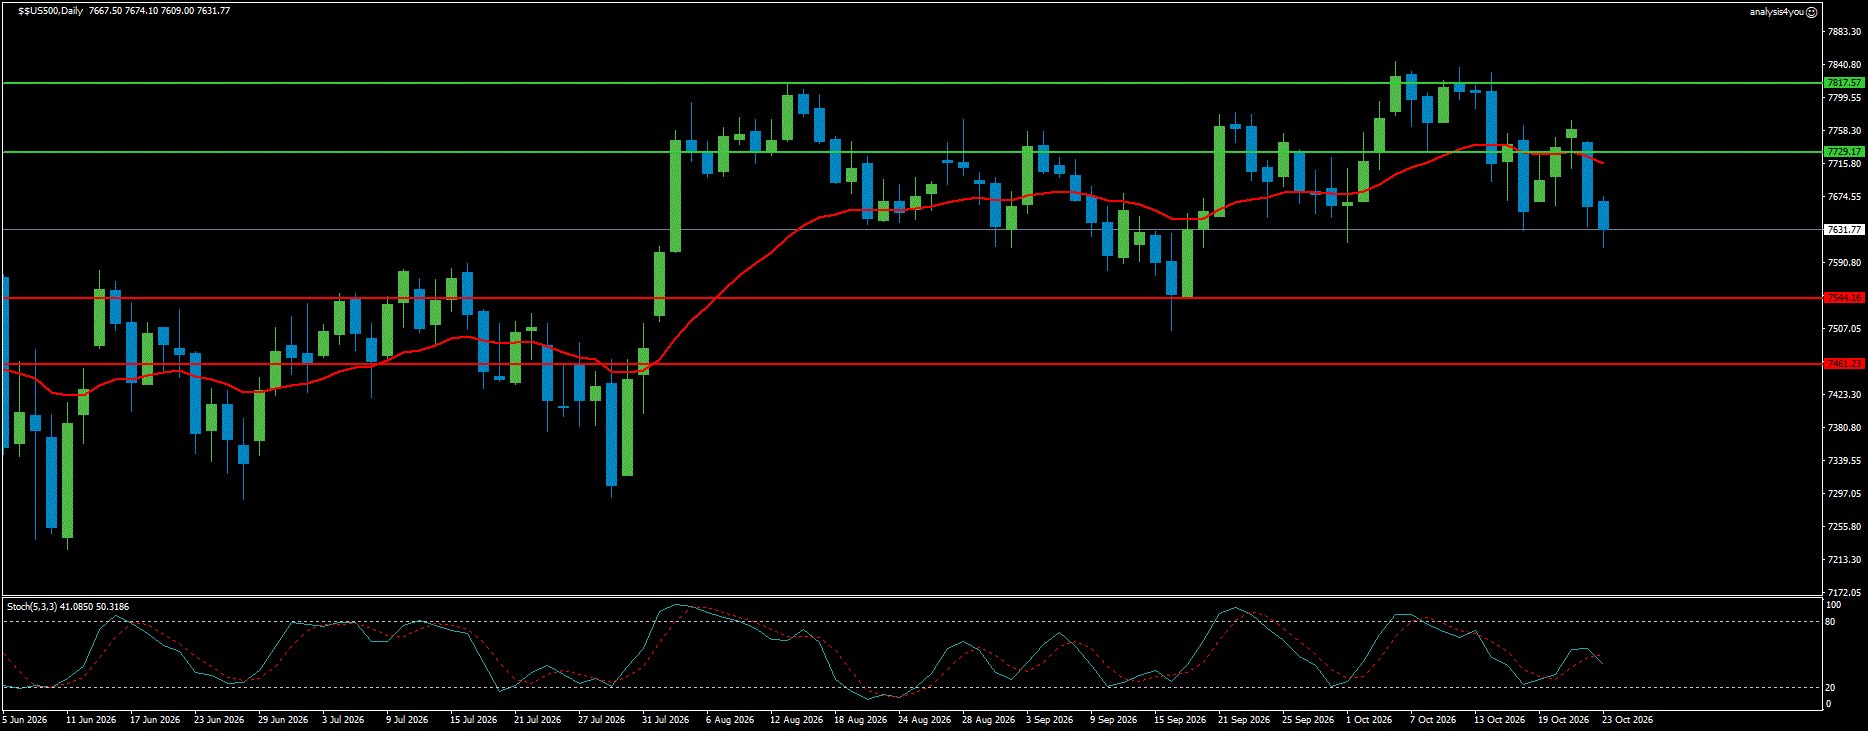
US500: From AI Fears to Oil Fears (7,632)
Trend: Neutral | Sentiment: Negative
The S&P 500 ended about 0.5% lower after two sessions that captured the market's dual fears. Thursday's sell-off hit chip and AI-related names on profitability worries, and Friday's oil above 104 hit transportation and consumer discretionary stocks. Breadth was severe on Friday: nearly three in four S&P 500 stocks fell, and the Nasdaq logged 74 new highs against 334 new lows. Price is below the 20-day MA, which has turned lower after supporting the market since September, and the Stochastic is falling. A hawkish Fed with dissents would revive yield pressure on growth stocks, while a balanced hold would allow a recovery. WTI above 110 would revive stagflation fears. Mega-cap tech earnings add a sector-specific catalyst.
Resistance: 7,729; 7,818 | Support: 7,544; 7,461
Bias: Reclaiming 7,729 would ease near-term pressure. A break below 7,544 opens 7,461.
Commodities
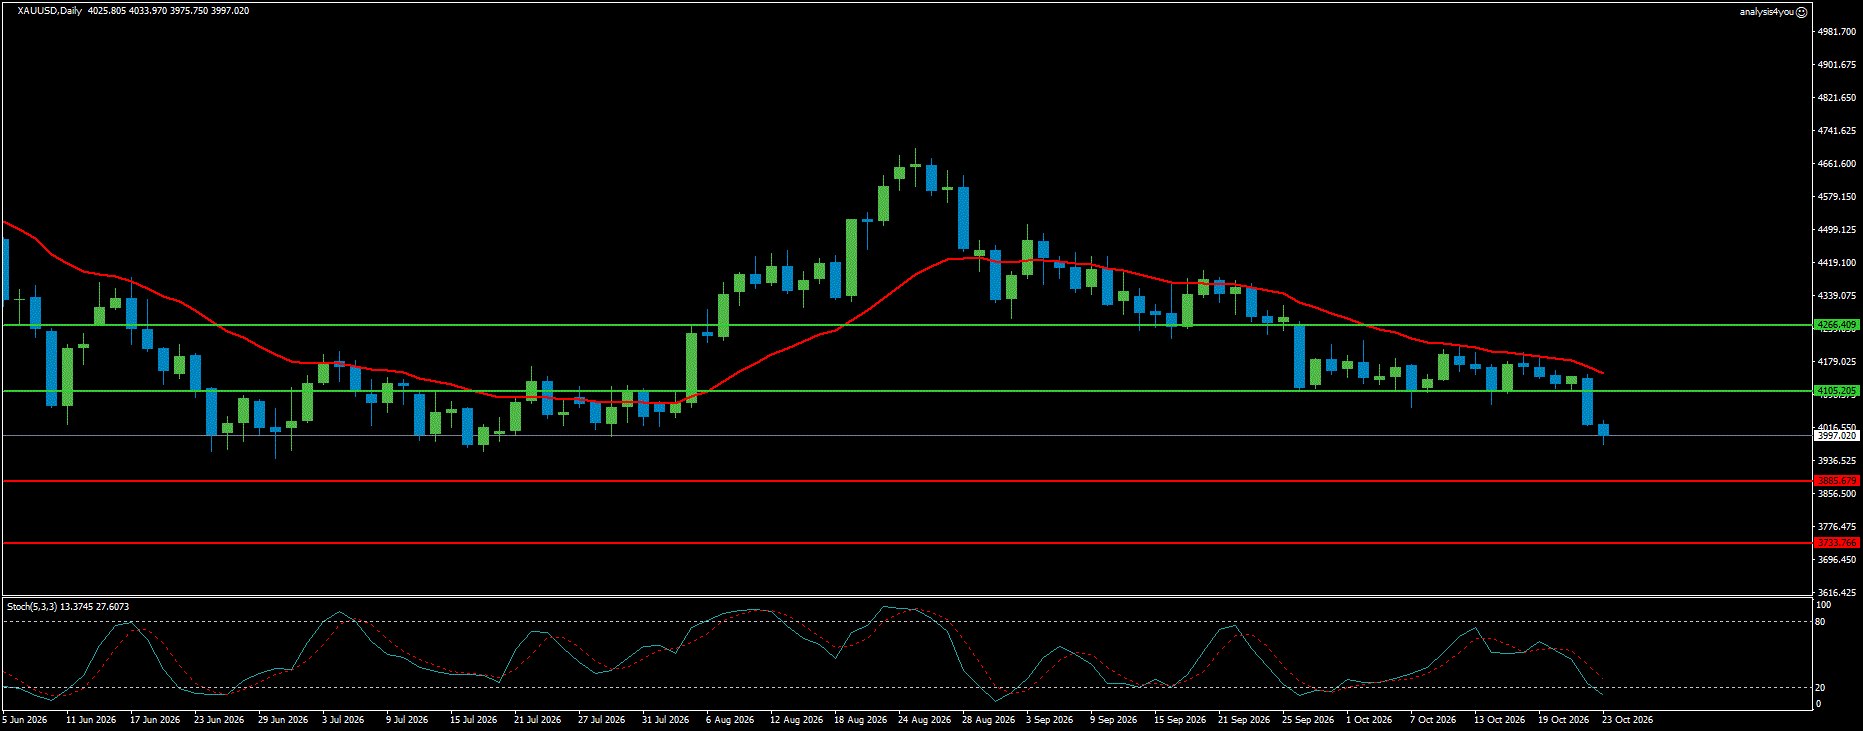
Gold: Oil-Driven Inflation Fear Overrides the Yield Signal (3,997)
Trend: Bearish | Sentiment: Negative
Gold fell about 4% and broke below 4,000 despite falling Treasury yields. ING says markets are focused on higher oil prices and what they mean for central bank policy, rather than using Gold as a safe haven or a yield trade. When investors worry that oil above 100 forces more aggressive hikes, higher real rates weigh on Gold, and it can be sold to fund losses elsewhere. Price broke sharply below the 20-day MA with the Stochastic deeply oversold. TD Securities expects ETF and central bank flows to support the 3,975 to 4,000 region, which has held twice this month, while OCBC notes any rebound would be fragile while oil drives the narrative.
Resistance: 4,105; 4,266 | Support: 3,886; 3,734
Bias: Oversold conditions could allow a bounce toward 4,105, and a dovish Warsh could add to it. A hawkish hold would add pressure toward 3,886, and a clean break there opens 3,734.
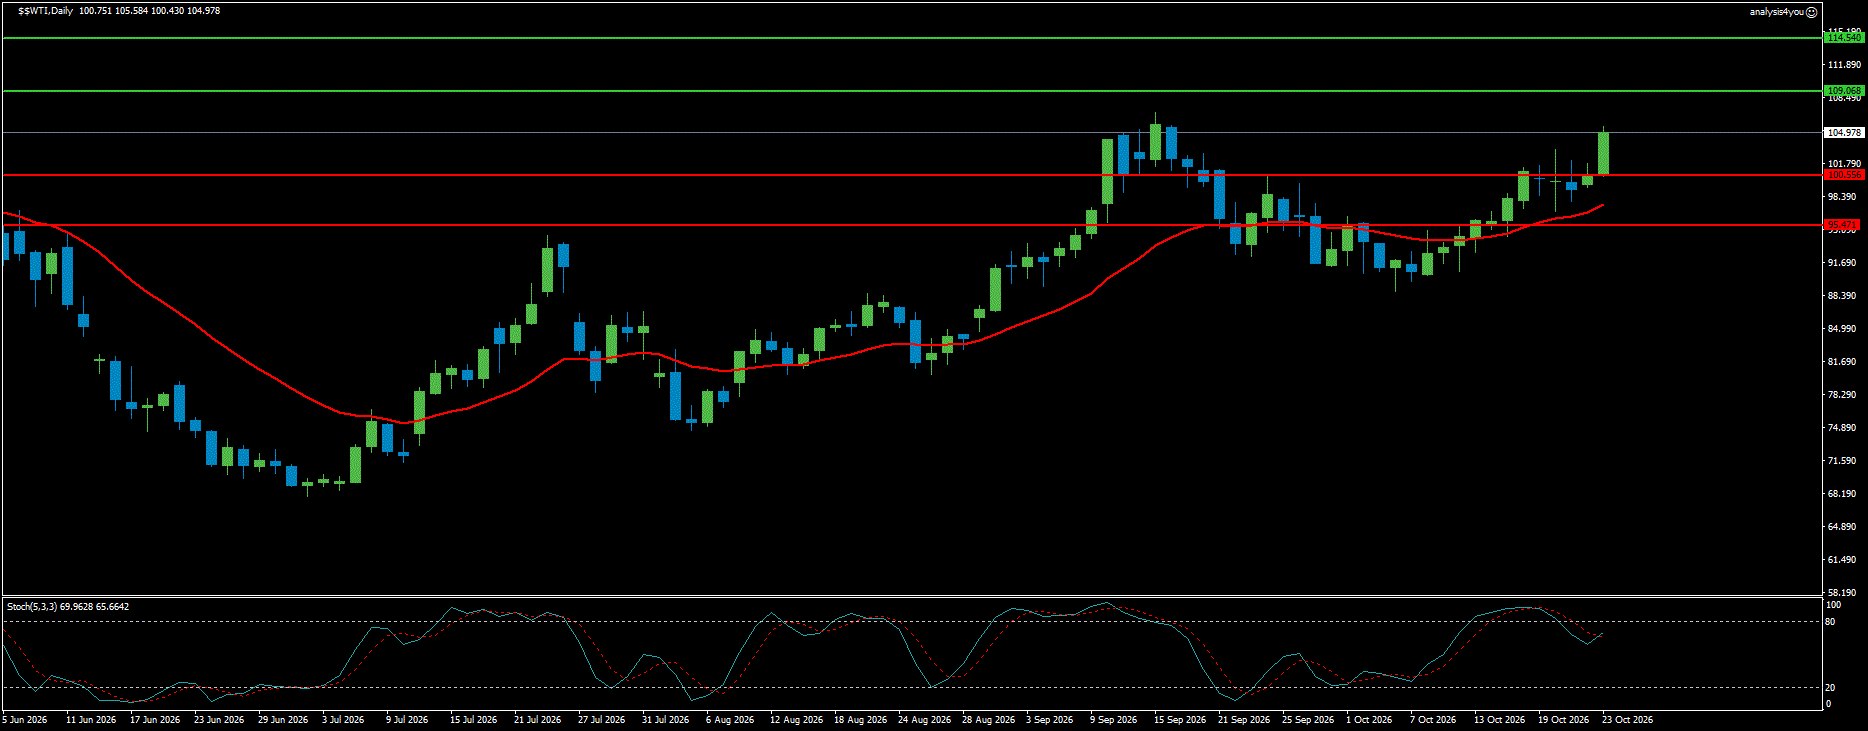
WTI Crude Oil: The War Premium Has No Ceiling Yet (104.98)
Trend: Bullish | Sentiment: Positive
WTI broke above 100 and kept climbing, gaining about 4% on Friday alone as Middle East hostilities intensified. Reports of US-Israel post-midterm strike planning, IRGC attacks on Hormuz shipping, a mine-triggered tanker explosion and a 3.1 million barrel US crude inventory draw, leaving stocks about 3% below the five-year average, drove the move. One warning sign: CFTC data show speculators cut net long positions while prices rose. That divergence suggests the rally is running ahead of positioning and could reverse sharply on a diplomatic headline. Price is well above the 20-day MA with the Stochastic rising. The midterm constraint on US military action ends November 3, and WTI above 110 would add about 0.4 percentage points monthly to headline CPI.
Resistance: 109.07; 114.54 | Support: 100.56; 95.47
Bias: Holding 100.56 keeps the uptrend intact toward 109.07 and 114.54. Any de-escalation or Hormuz deal headline could trigger a sharp reversal toward 95.47.
Cryptocurrencies
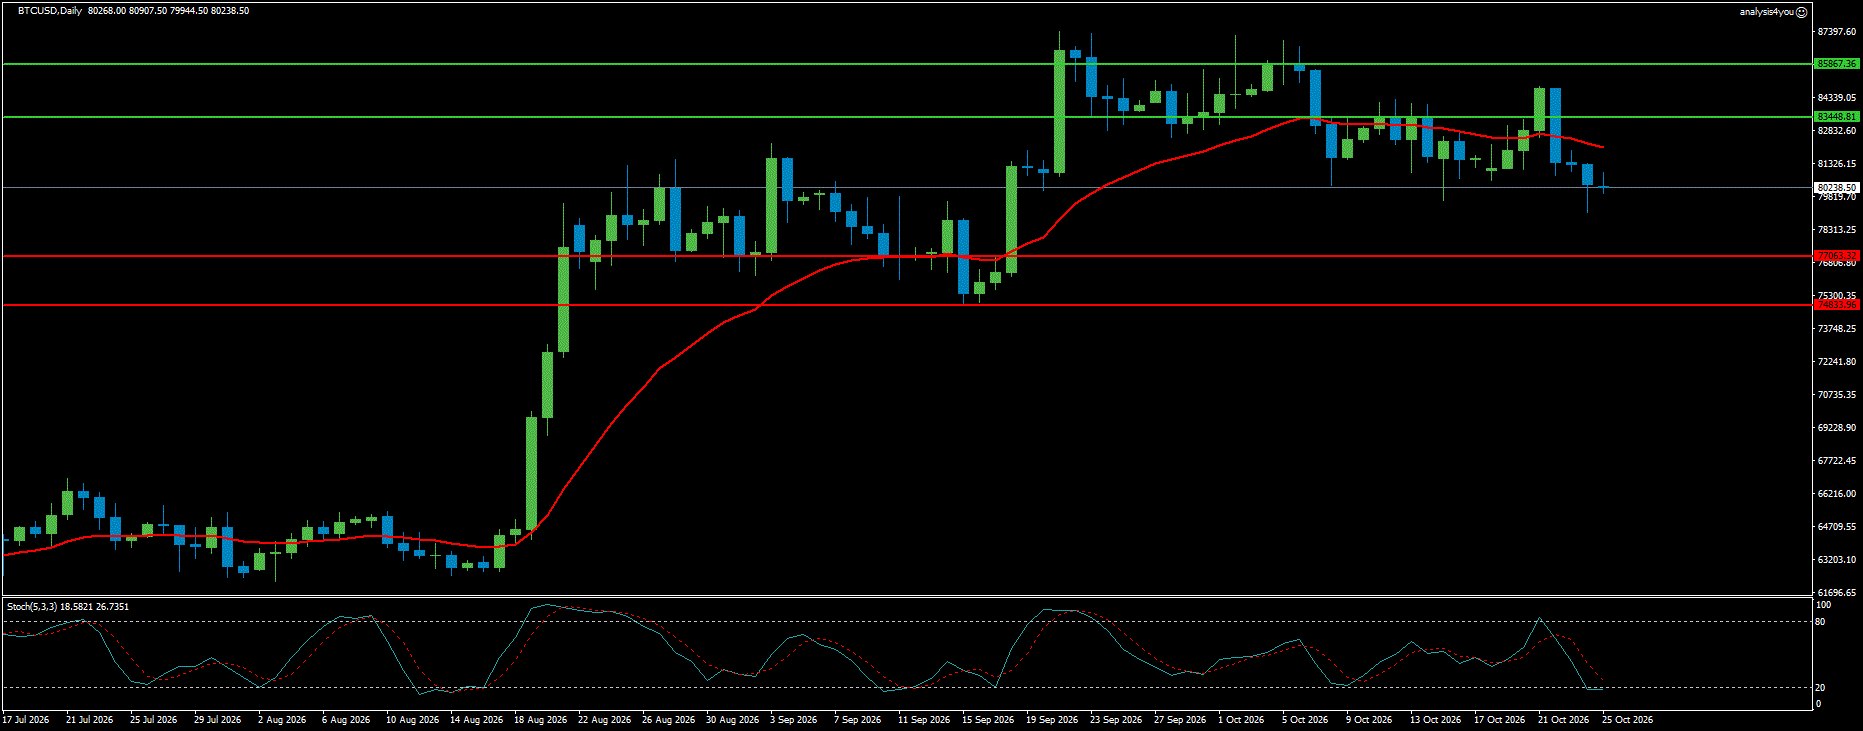
Bitcoin: Stuck at the ETF Cost Basis (80,239)
Trend: Bullish | Sentiment: Mixed
Bitcoin went nowhere for the week, starting and ending near 81,000 despite moves toward 85,000 mid-week. On Thursday, heavy ETF outflows, following over 1 billion dollars of early-week inflows, combined with long liquidations to pull price back below 81,000. That area is widely seen as the spot ETF cohort's average cost basis and is being tested rather than firmly defended. Buyers have so far protected the 80,000 zone, but price is below a falling 20-day MA, and the Stochastic is oversold. Corporate accumulation continues to provide an underlying bid. The CLARITY Act House floor vote is expected this month without a confirmed date.
Resistance: 83,449; 85,867 | Support: 77,063; 74,834
Bias: A balanced or dovish Fed would improve risk sentiment and allow a recovery toward 83,449, while the oversold Stochastic supports a technical bounce. A daily close below the 80,000 zone opens 77,063 and 74,834.
Week Ahead Outlook
Base case: hawkish hold, ECB caveat, oil stable (about 35%): Warsh delivers a hawkish hold with one or two dissents in favor of hiking, confirming December as the base case. Lagarde holds and keeps December guidance while acknowledging French spread risks. WTI stays between 100 and 109. The Dollar holds above 100.67, EUR/USD tests the 200-week SMA near 1.1109, Gold bounces toward 4,105 but stays capped, the S&P 500 ranges between 7,544 and 7,729, and Bitcoin recovers toward 83,449.
Bull case for risk assets: dovish Fed, diplomatic progress (about 25%): Warsh acknowledges oil-driven inflation as supply-side and reduces December hike urgency, while a diplomatic signal suggests Iran strikes could be delayed beyond the midterms. WTI falls toward 100.56 and possibly 95.47, the Dollar softens toward 100.67, Gold rebounds toward 4,105 and 4,266, the S&P 500 recovers above 7,729, EUR/USD bounces toward 1.1312, and Bitcoin breaks above 83,449 toward 85,867.
Bear case: hawkish surprise plus oil above 109 (about 40%): Warsh sounds more hawkish than expected, with multiple dissents and an explicit December pre-commitment, while strike-planning reports intensify and WTI heads toward 114.54. GDP at 3.5% or above with core PCE at 0.4% would add to the pressure. The Dollar breaks through 102.25 toward 103.18, EUR/USD breaks below 1.1109 toward 1.1063 and tests 1.1000, Gold breaks below 3,886 toward 3,734, the S&P 500 tests 7,544 and 7,461, and Bitcoin tests 77,063. Given the oil trajectory and the Fed's hawkish posture, this is currently the highest-probability scenario.
Five central banks, a UK budget, US GDP, core PCE and WTI near 110 all land before Friday's close. When both the safe-haven and the yield relationships fail at once, oil is the dominant pricing mechanism, and the Fed's response on Wednesday sets the tone through the November 3 midterms. The goal is always to get profit, not to trade as many as possible.
Disclaimer: This analysis is for educational and informational purposes only and does not constitute investment advice. Trading leveraged products such as Forex, Gold, commodities, indices and cryptocurrencies carries a high level of risk and may not be suitable for all investors.